
……The mortgage scheme offers eligible Nigerians abroad financing at 9% interest, but stakeholders urge stronger property verification and longer repayment terms.
For Nigerians living abroad, owning a home in Nigeria often represents both a financial investment and an emotional connection to their homeland. However, distance, unreliable developers, documentation challenges and limited access to mortgage financing have complicated the process.
The Federal Mortgage Bank of Nigeria (FMBN) is seeking to address some of these challenges through its Diaspora National Housing Fund Mortgage Loan.
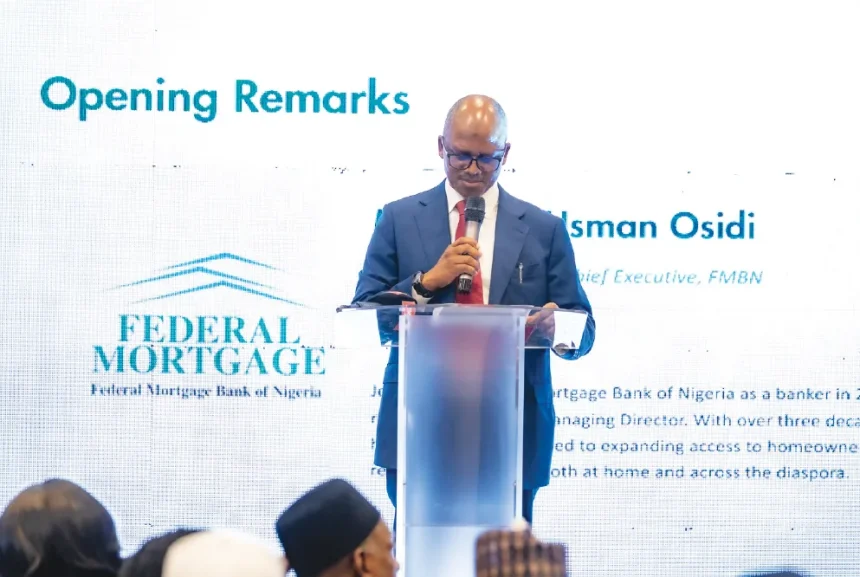
The scheme, officially launched in London on August 7, 2026, allows eligible Nigerians living abroad to access mortgage financing for residential properties in Nigeria.
Developed in collaboration with the Nigerians in Diaspora Commission (NiDCOM), the initiative expands the National Housing Fund (NHF) scheme beyond Nigeria’s borders.
Nigerians Abroad Can Access up to ₦100m
Under the scheme, eligible Nigerians in the diaspora can access mortgage financing of up to ₦100 million, subject to affordability assessments and applicable requirements.
The facility carries an interest rate of 9% per annum, with a maximum repayment period of 10 years.
FMBN said applicants can register under the NHF scheme, complete their Know Your Customer (KYC) requirements and make contributions remotely through its digital platforms.
The scheme is designed to reduce the need for Nigerians abroad to travel to Nigeria simply to begin the mortgage application process.
FMBN officially confirmed the launch and the financing terms in a statement issued after the London event.
Digital Application Process
The mortgage initiative includes a digital registration system intended to simplify access for Nigerians living outside the country.
Applicants must meet the scheme’s eligibility requirements, including Nigerian citizenship, verifiable income, NiDCOM verification and compliance with NHF contribution conditions.
The official application portal provides information on registration, verification, application status and relevant documentation.
The scheme’s published terms also indicate that applicants must be first-time NHF loan beneficiaries and maintain consistent NHF contributions for the required period.
Housing Stakeholders Welcome Initiative
Founder of the Africa International Housing Show, Festus Adebayo, described the scheme’s remote-access structure as one of its major advantages.
Adebayo said the initiative could provide stronger institutional support for Nigerians abroad who have experienced difficulties with property developers and informal housing arrangements.
He, however, stressed that property quality and delivery must receive the same attention as mortgage access.
According to him, FMBN should verify properties before releasing funds to developers to protect diaspora investors from fraudulent operators.
Developers Must Meet Verification Requirements
The President of the Real Estate Developers Association of Nigeria, Prince Akintoye Adeoye, also welcomed the initiative.
Adeoye explained that FMBN would not simply release funds to any developer but would work with developers offering properties suitable for purchase under the scheme.
He said prospective homeowners would first identify a property before proceeding with the mortgage application.
The arrangement places emphasis on property selection, documentation and the eligibility of developers participating in the financing process.
Stakeholders Debate Ten-Year Repayment Period
Although the 9% interest rate has attracted attention, Adebayo raised concerns about the scheme’s maximum 10-year repayment period.
He argued that a longer repayment period could make the facility more accessible by reducing monthly repayment obligations.
FMBN’s conventional NHF mortgage scheme for eligible contributors in Nigeria provides a maximum repayment period of 30 years, according to the supplied report.
Adeoye, however, argued that Nigerians living abroad should take advantage of the opportunity despite the shorter repayment period.
The debate reflects the challenge of balancing affordable monthly repayments with the need for sustainable mortgage financing.
Concerns Over Possible Abuse
Adeoye also warned that the scheme must not be diverted to wealthy Nigerians who may not genuinely require the financing.
He urged FMBN to strengthen its due diligence and ensure that the facility reaches its intended beneficiaries.
The concern highlights the importance of transparent eligibility requirements, effective verification and accountability throughout the application and disbursement process.
FMBN’s Wider Housing Finance Strategy
The Diaspora Mortgage Loan forms part of FMBN’s broader housing finance mandate, which includes products such as Rent-to-Own, Home Renovation Loans, Cooperative Housing Development Loans and Individual Construction Loans.
The bank has also been developing additional financing options, including a Rent Assistance Loan and a Non-Interest Mortgage Loan window.
The diaspora scheme is expected to support housing construction, strengthen mortgage access and encourage investment in Nigeria’s housing sector.
However, its long-term impact will depend on effective implementation, reliable property verification, quality housing delivery and protection for borrowers.
For Nigerians abroad, the scheme’s success will ultimately be measured by whether it makes homeownership safer, more transparent and more accessible.