
More Nigerian workers are turning to their pension savings to raise equity contributions for residential homeownership as rising property costs and declining purchasing power make it increasingly difficult to buy homes.
Data from the National Pension Commission (PenCom), as reported by Financial Vanguard, showed that 28,437 pension contributors accessed their Retirement Savings Accounts (RSAs) for homeownership equity contributions in the first quarter of 2026.
The figure represents a 284.3 per cent increase from the 7,399 contributors who accessed their pension savings for the same purpose in the fourth quarter of 2025.
The amount withdrawn also increased sharply. A total of N92.7bn was accessed from the contributors’ RSAs for residential homeownership equity contributions in Q1 2026, compared with N28.27bn in Q4 2025.
That represents a 227.9 per cent increase in the value of pension savings accessed within one quarter.
The increase in both the number of contributors and the amount accessed highlights the growing role of pension savings in helping workers meet the upfront financial requirements for homeownership.
It also reflects the widening gap between household incomes and the cost of residential property, particularly as rents, construction costs and mortgage-related expenses continue to rise.
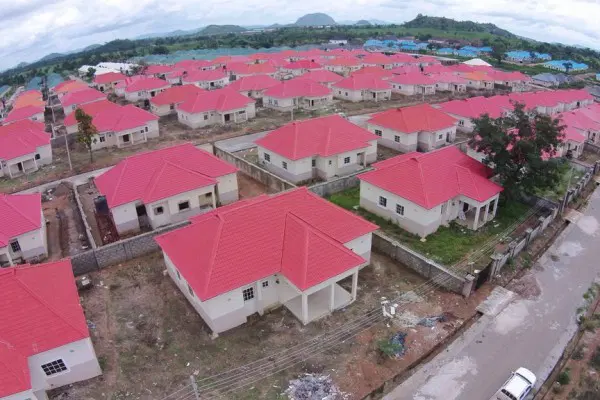
Nigeria’s housing deficit was estimated in the report at 14.9 million units, while experts put the funding requirement for bridging the gap at about N21tn.
Despite the existence of the National Housing Fund (NHF), which was established as a financing mechanism to improve access to housing finance, stakeholders continue to raise concerns about workers’ ability to access loans through the scheme.
How pension savings can support homeownership
Under the Contributory Pension Scheme (CPS), eligible Retirement Savings Account holders can access up to 25 per cent of their RSA balances as equity contributions for residential mortgage financing.
The provision applies to active RSA holders who have contributed to the CPS for at least 60 months and are seeking to purchase their first homes, in line with Section 89(2) of the Pension Reform Act 2014.
PenCom’s guidelines provide that where 25 per cent of a contributor’s RSA balance exceeds the required equity contribution, the contributor can only access the amount needed for the equity contribution.
Where the 25 per cent is insufficient, contributors may use voluntary contributions where applicable, while personal pension contributors may also access the contingency portion under the relevant guidelines.
Where the available pension resources remain insufficient to meet the required equity contribution, the RSA holder is expected to provide the balance to the mortgage lender.
The policy covers pension contributors who are actively employed, including salaried workers and eligible self-employed contributors.
Workers still struggle to access NHF loans
The growing reliance on pension savings comes amid concerns over the effectiveness of the National Housing Fund in providing affordable mortgage finance to workers.
President of the Nigeria Labour Congress, Joe Ajaero, said workers had continued to face difficulties accessing housing loans despite regular deductions from their salaries for the NHF.
Ajaero said the government had consistently deducted the mandatory 2.5 per cent contribution from workers’ salaries, but argued that the Federal Mortgage Bank of Nigeria had not adequately communicated information about the contributions made into workers’ NHF accounts.
According to him, the lack of information has frustrated workers who are unable to take full advantage of the scheme.
He also raised concerns about delays in processing housing loans.
Ajaero said the NHF Act provides for a 90-day period from loan application to disbursement, but claimed that delays in approving loans had forced some workers to abandon their applications.
He further alleged that some applicants had resorted to third-party agents to accelerate the process, sometimes at unofficial costs.
“Despite the increase in the total pool in NHF, workers were still unable to get loans to get shelter,” he said.
Experts back pension-backed homeownership
Urban planner and environmentalist Michael Simire said the difficult economic environment, including naira depreciation, had made homeownership increasingly difficult for many Nigerians.
He said the pension scheme was nevertheless creating an avenue through which some workers could raise the funds required to purchase homes.
Simire also pointed to the existence of vacant residential and commercial properties, arguing that affordability remained a major reason many Nigerians could not take up available housing.
Director of the Centre for Pension Rights Advocacy, Ivor Takor, described the inclusion of homeownership within the pension scheme as a positive development.
However, he said Nigerians who were outside the pension scheme should also have access to housing loans at moderate interest rates.
Takor called for additional measures such as subsidies, tax concessions and appropriate private, cooperative and public-sector housing initiatives to expand access to affordable homes.
High property costs weigh on housing demand
Principal Partner of M.I. Okoro and Associates, Meckson Innocent Okoro, said the difficult economic environment had contributed to weak demand for residential mortgages and real estate.
He said high exchange rates had pushed up the cost of inputs across the property sector, making homes increasingly unaffordable for average investors.
According to Okoro, the high cost of property also creates longer investment recovery periods.
He illustrated the pressure by comparing a property that previously cost N30m with one that could now cost N90m, arguing that an investment that might previously have been recovered within five years could now require a much longer period.
Okoro said the entry of pension savings into the housing market could help moderate property prices and increase homeownership if the scheme is effectively implemented.
Former President of the Pension Fund Operators Association of Nigeria (PenOp), Olumide Oyetan, also said the residential mortgage scheme could improve contributors’ welfare and have a positive impact on the wider economy.
He said successful implementation of the initiative would improve people’s welfare and contribute to economic progress.
Housing finance remains a major challenge
The sharp rise in pension-backed housing finance comes as Nigeria continues to face a significant gap between housing supply, property prices and household purchasing power.
While allowing eligible workers to use part of their retirement savings provides an additional source of equity for home purchases, stakeholders continue to point to the need for broader reforms in mortgage finance and housing delivery.
The figures show that pension savings are becoming an increasingly important source of housing finance for Nigerian workers.
However, the continued increase in the amount workers need to withdraw from retirement savings also highlights the financial pressure prospective homeowners face in raising the initial capital required to enter the housing market.
For workers outside the pension scheme, stakeholders say alternative financing mechanisms will also be required if homeownership is to become more accessible.
The combination of affordable mortgage financing, improved access to housing loans, lower construction costs and increased housing supply remains central to efforts to address Nigeria’s housing crisis.