
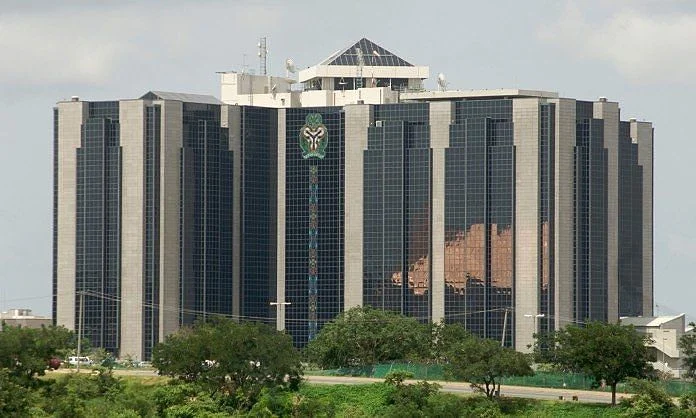
Personal loans obtained by Nigerians rose to an estimated N2.06tn in May 2026 as consumer credit continued to expand amid persistent cost pressures and weak consumer spending, according to the latest Economic Report of the Central Bank of Nigeria.
The figure, derived from data contained in the CBN’s May 2026 Economic Report, represents about 64.78 per cent of the N3.18tn total consumer credit outstanding during the month.
The report covers developments across the real, fiscal, financial and external sectors of the Nigerian economy.
According to the apex bank, consumer credit increased by 1.60 per cent from N3.13tn in April to N3.18tn in May, indicating that Nigerians borrowed an additional N50bn within one month.
The CBN attributed the increase to growth in both personal and retail loans, which rose by 1.98 per cent and 0.90 per cent respectively.
The bank said personal loans remained the largest component of consumer credit, accounting for 64.78 per cent, while retail loans represented the remaining 35.22 per cent.
Based on those proportions, personal loans stood at approximately N2.06tn at the end of May, while retail loans amounted to about N1.12tn.
The 1.98 per cent month-on-month increase in personal loans represents an increase of roughly N40bn during the period. Retail loans, which are more directly associated with the purchase of goods and services, recorded a slower 0.90 per cent increase.
The figures indicate that personal borrowing remained the main driver of Nigeria’s consumer-credit market, accounting for nearly two-thirds of outstanding consumer credit.
Economic pressures drive borrowing
The increase in borrowing occurred against a challenging economic backdrop, with the CBN reporting weak economic activity during May.
The bank’s composite Purchasing Managers’ Index stood at 49.60 points in May, slightly higher than the 49.40 points recorded in April but still below the 50-point mark that separates expansion from contraction.
The CBN said the contraction reflected subdued demand, declining new orders and elevated production costs. It also identified weak consumer spending and higher energy-related costs as major pressures on the industry and services sectors.
Inflation also remained elevated during the period. Headline inflation increased to 15.93 per cent in May from 15.69 per cent in April, with the CBN attributing the increase to persistent cost pressures and higher energy prices.
However, month-on-month inflation slowed to 1.75 per cent in May from 2.13 per cent in April.
The combination of rising consumer credit and weak consumer spending indicates that more households were turning to credit at a time when living and operating costs remained under pressure.
More Nigerians borrowing for consumption
The trend is also reflected in findings from the 2026 Access to Financial Services in Nigeria Survey by Enhancing Financial Inclusion & Advancement.
The survey found that 40.8 per cent of Nigerians borrowing from formal financial institutions now use loans mainly for coping and consumption needs, up from 31.7 per cent in 2023.
The increase of 9.1 percentage points made coping and consumption the largest purpose of formal borrowing, overtaking productive enterprise borrowing, which fell from 40.2 per cent in 2023 to 34.3 per cent in 2026.
Borrowing for household assets also declined from 25.2 per cent to 23.4 per cent.
The report warned that the shift towards consumption and coping borrowing raises concerns about whether credit is helping households build productive capacity or simply helping them manage financial pressures.
The survey covered 18,679 adults across Nigeria’s 36 states and the Federal Capital Territory, with data collected between April and June 2026 under the supervision of the National Bureau of Statistics.
Formal credit use increased from six per cent of adults in 2023 to 10 per cent in 2026, representing about 11.9 million Nigerians borrowing from regulated financial institutions.
When informal sources were included, 36 per cent of adults had access to some form of credit.
Credit use among informally employed Nigerians tripled from five per cent to 15 per cent during the period. Among Nigerians aged between 18 and 35, borrowing increased from four per cent to 10 per cent.
Borrowing among business owners also rose from four per cent to 10 per cent, while farmers recorded an increase from two per cent to six per cent.
Borrowers face repayment pressure
Despite the increase in access to credit, the survey highlighted significant financial stress among borrowers.
About 45.8 per cent of formal-credit users reported experiencing some or serious repayment stress, while 83.8 per cent reported ongoing financial stress.
The findings suggest that the growth in credit access has not necessarily translated into improved financial wellbeing for many Nigerians.
The survey also found that overall financial inclusion had reached 79 per cent, equivalent to about 94.2 million adults, while formal financial inclusion stood at 73 per cent.
However, only about one-quarter of Nigerian adults were considered financially healthy.
EFInA Chief Executive Officer, Foyinsolami Akinjayeju, said the findings showed that Nigeria needed to look beyond simply increasing access to financial services and focus on whether those services were improving people’s financial wellbeing.
EFInA Board Chairman, Dr Agnes Martins, similarly said access to financial services should be viewed as the beginning rather than the ultimate objective of financial inclusion.
The latest CBN figures therefore show a continued expansion in consumer credit, while the financial inclusion survey highlights a shift in the reasons Nigerians are borrowing, with a growing share turning to loans to cope with household pressures and consumption needs.