
Nigeria Needs Cheaper Construction Loans, Better Urban Planning to Solve Housing Crisis
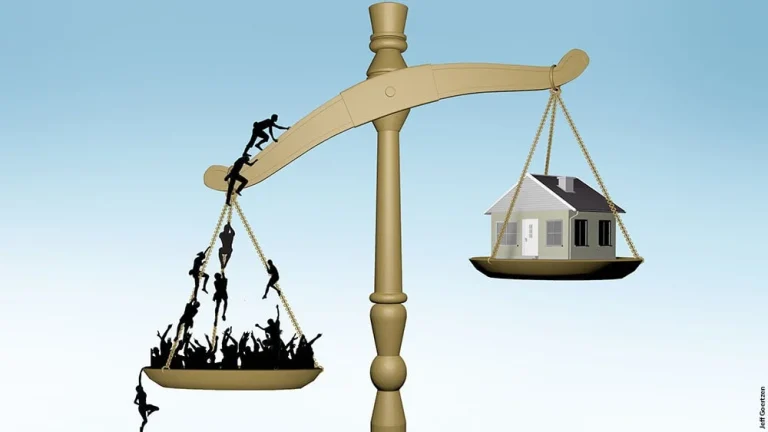
Nigeria must look beyond mortgage financing and adopt broader housing policies that address construction costs, land administration, infrastructure and urban planning to make homes more affordable, according to construction and project management professional Jimoh Foluso.
Foluso argued that the country’s housing crisis cannot be resolved by simply reducing mortgage interest rates or extending loan repayment periods, noting that the cost of producing houses remains a major obstacle to affordability.
In an opinion article published by PUNCH, he said successive governments had introduced housing initiatives and announced ambitious construction targets, yet millions of Nigerians continued to struggle to access decent and affordable accommodation.
He maintained that Nigeria’s housing challenge was not just a shortage of houses but a structural problem involving how homes are financed, constructed and integrated into urban communities.
High Construction Costs Driving Property Prices
Foluso identified expensive commercial loans, currency fluctuations, rising building material prices, inadequate infrastructure and lengthy approval processes as some of the factors increasing the cost of housing development.
He explained that developers must account for land acquisition, cement, steel, labour, transportation, electricity, water infrastructure and professional fees before determining the final selling or rental price of a property.
According to him, these expenses are eventually transferred to homebuyers and tenants, making housing increasingly unaffordable.
He therefore argued that cheaper mortgages alone would not address the problem because mortgage financing determines how buyers pay for homes, while construction financing significantly influences how much those homes cost to produce.
Proposal for Long-Term Housing Construction Loans
To address the financing gap, Foluso proposed establishing a dedicated long-term construction finance facility that would allow qualified developers to access loans at approximately seven to nine per cent interest annually.
He suggested repayment periods of between 10 and 20 years, subject to project cash flows and risk assessments.
The proposed facility could be funded through a combination of government capital, development finance institutions, pension and institutional investments, guarantees and private-sector participation.
He also recommended that financing should be released in stages based on independently verified construction milestones to ensure accountability and prevent misuse of funds.
Developers seeking access to the facility, he said, should demonstrate a credible track record, proper land documentation, relevant approvals, technical capacity and realistic project cost estimates.
Foluso stressed that the objective should be to reduce the cost of producing affordable homes rather than provide indiscriminate subsidies to property developers.
Nigeria Urged to Embrace Better-Planned Cities
Beyond financing, the construction professional called for a shift away from excessive dependence on sprawling, low-density housing estates located far from established urban centres.
He explained that developments on the outskirts of cities may appear affordable because of cheaper land prices, but residents often face additional expenses associated with transportation, poor road networks and limited access to essential services.
According to him, the actual cost of housing should include the expenses of living in and accessing the surrounding urban environment, not merely the purchase price of the property.
He advocated well-planned vertical developments, including mid-rise and high-rise residential buildings, where supported by infrastructure capacity, building regulations and market demand.
Such developments, he argued, could accommodate more households on strategically located land while reducing infrastructure costs per household.
However, he cautioned that higher-density developments must be supported by adequate roads, drainage, water supply, electricity, sanitation, healthcare facilities, schools and recreational spaces.
Build-to-Rent Model Proposed as Housing Solution
Foluso also called for the expansion of rental housing as a central part of Nigeria’s national housing strategy.
He argued that housing policies have placed too much emphasis on homeownership, overlooking Nigerians who cannot afford mortgage deposits or do not qualify for housing loans.
He identified young professionals, civil servants, artisans, students, newly married couples and workers who relocate for employment as groups that require secure and affordable rental accommodation.
He proposed adopting a Build-to-Rent model in which government institutions, private developers and institutional investors finance residential developments specifically for long-term rental rather than immediate sale.
Under the arrangement, developers would maintain professionally managed rental properties, generating long-term income while providing tenants with more secure accommodation.
He said the model should prioritise affordable studios, one-bedroom and two-bedroom apartments located close to employment centres or reliable public transportation.
To ensure affordability, he recommended the use of public land, infrastructure support, concessional construction financing and carefully structured investment incentives.
He also called for transparent tenancy agreements, proper property maintenance, clear service-charge arrangements and safeguards against arbitrary rent increases.
Nigeria’s Housing Deficit and the Need for Reliable Data
Foluso noted that the Federal Ministry of Housing and Urban Development announced in January 2026 that Nigeria’s 2025 housing deficit stood at approximately 14.925 million units.
He cautioned against continuing to rely on older estimates of 28 million housing units without explaining their sources and methodology.
He also distinguished the housing deficit figure from the broader estimate of approximately 15.2 million homes classified as inadequate or structurally defective.
According to him, reliable housing data is essential for developing effective policies and measuring progress.
Lessons from Singapore’s Housing Development Model
The article also referenced Singapore’s housing development strategy as an example of how sustained government investment, coordinated land policies, long-term financing and integrated urban planning can support large-scale housing delivery.
Singapore’s Housing and Development Board, established in 1960, reportedly constructed more than 21,000 flats within its first three years and has since delivered over 1.25 million flats.
Foluso said Nigeria could draw lessons from the country’s institutional approach while adapting its policies to local land ownership structures, economic conditions and housing needs.
He emphasised that successful housing delivery requires more than constructing residential buildings, stressing the importance of connecting homes to employment opportunities, transportation and essential public services.
Call for a Comprehensive National Housing Strategy
Foluso outlined several priorities for improving housing delivery in Nigeria, including establishing long-term construction financing, reforming land administration, promoting planned urban density, modernising construction methods and expanding professionally managed rental housing.
He maintained that these interventions must work together, warning that cheaper financing would have limited impact without effective urban planning and infrastructure development.
He also argued that affordable housing should be measured by the actual cost households incur to acquire or occupy properties, rather than the marketing claims attached to housing developments.
He concluded that Nigeria needs a housing delivery system capable of serving both prospective homeowners and tenants, rather than relying primarily on mortgage schemes and isolated housing estate projects.