
Nigeria’s housing sector needs stronger institutions, long-term financing and a clearer division of responsibilities between government and the private sector to make home ownership more accessible, according to housing finance commentator Victor Ogiemwonyi.
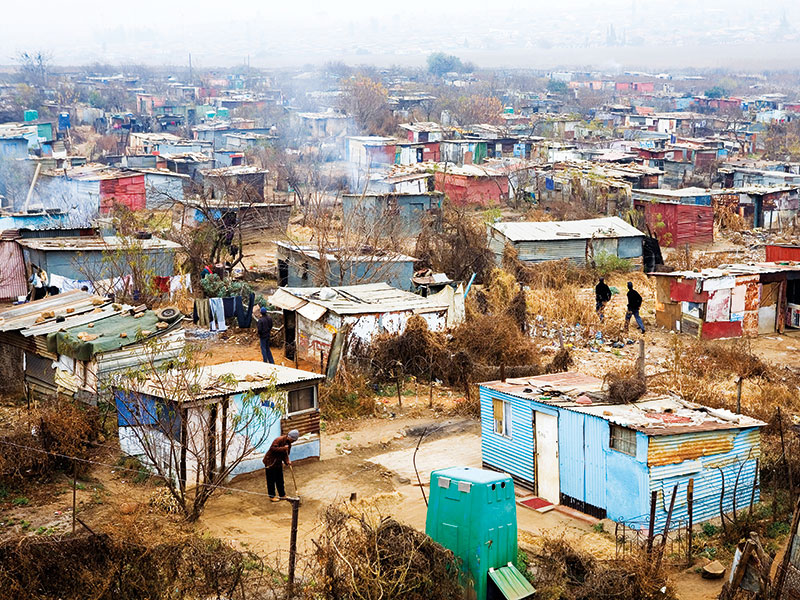
The country’s housing market faces a structural mismatch between demand, supply and finance. Rapid urbanisation, rising rents, limited access to serviced land and inadequate long-term mortgage funding have placed home ownership beyond the reach of many households.
Despite growing construction activity, affordable housing remains difficult to secure, particularly in major urban centres such as Lagos. The challenge extends beyond building more homes to creating an effective system that connects land, infrastructure, regulation, developers and long-term capital.
Ogiemwonyi argues that addressing these constraints requires government to concentrate on land provision, infrastructure, regulation and market-enabling institutions, while private developers and financial institutions take responsibility for construction and mortgage lending.
Rising Demand, Limited Housing Supply
Nigeria’s population growth and rapid urbanisation continue to place pressure on housing supply. In Lagos, visible construction activity has not eliminated rising rents or the shortage of affordable homes.
The underlying problem, according to Ogiemwonyi’s analysis, is the absence of a properly organised property market capable of connecting land, infrastructure, finance and housing demand.
He argues that expanding construction alone will not resolve the crisis unless the institutions supporting housing development and ownership also become more effective.
Public Housing Institutions Face Delivery Challenges
Institutions such as the Federal Mortgage Bank of Nigeria (FMBN) and state housing agencies, including the Lagos State Development and Property Corporation (LSDPC), have struggled to deliver affordable housing at the scale required.
Bureaucratic processes, inconsistent implementation and changing policy priorities have weakened their effectiveness.
Ogiemwonyi maintains that state housing agencies should continue to prioritise affordable homes for workers, even when they partner with private developers to mobilise funding.
While private developers must generate commercial returns, public housing agencies have a broader social responsibility. Their partnerships, he argues, should preserve affordability rather than focus exclusively on financial returns.
Land Administration And Regulation Need Reform
Cumbersome regulation, multiple taxes and levies, slow approvals and weaknesses in land administration increase transaction costs and discourage investment in the housing sector.
Digital land administration and Geographic Information Systems (GIS) could improve title processing, strengthen property records and make land and buildings easier to use as collateral.
However, implementation remains uneven across jurisdictions, limiting the potential benefits of these reforms.
Ogiemwonyi argues that more predictable land administration and simpler approval processes would help developers, lenders and individual homebuyers participate more effectively in the formal property market.
Lessons From Previous Housing Programmes
Nigeria’s previous public housing initiatives demonstrate the role government can play in making land and infrastructure available for development.
Programmes and estates such as Gowon Estate, Jakande housing estates, Dolphin Estate and Abraham Adesanya Estate illustrate different approaches to public-sector involvement in housing delivery.
The key lesson, Ogiemwonyi argues, is that government does not need to undertake every stage of construction.
By providing serviced land, essential infrastructure and timely approvals, government can create conditions in which private developers and individuals undertake more construction.
This approach could reduce the burden on public agencies while allowing them to concentrate resources on enabling infrastructure and affordable housing.
Mortgage Finance Remains A Major Constraint
Long-term finance remains one of Nigeria’s biggest barriers to wider home ownership.
Housing requires financing that borrowers can repay over extended periods. However, the country’s mortgage market lacks the depth and liquidity needed to support home ownership at scale.
FMBN currently performs several functions, including administering the National Housing Fund, providing mortgage finance and undertaking housing development-related activities.
Ogiemwonyi proposes a stronger emphasis on FMBN’s role as a secondary mortgage institution, while primary mortgage banks and other lenders originate and service housing loans.
Under this arrangement, the bank could help connect the capital market with mortgage lenders, creating a larger and more organised pool of long-term funding for housing.
Pension funds, insurance companies and other institutional investors could provide important sources of long-duration capital if appropriate investment structures, safeguards and risk-management mechanisms are established.
Housing Bonds Could Expand Long-Term Funding
Ogiemwonyi proposes a capital-market financing model built around housing bonds, mortgage-backed instruments and credit guarantees.
A reformed and adequately capitalised FMBN could raise long-term funding through capital-market instruments and help develop guarantees or other credit-enhancement structures to make suitable mortgage loans and housing projects more attractive to investors.
Such arrangements could also widen participation in housing finance by connecting institutional investors with properly structured mortgage assets.
Under the proposed model, borrowers would repay their mortgages over extended periods, potentially 15 to 20 years where household affordability and lending assessments support those terms.
Repayments and refinancing could then replenish available funds, allowing capital to support additional housing loans and projects.
The objective is to establish a more sustainable financing system that continuously mobilises capital for housing rather than relying predominantly on limited or short-term funding.
However, achieving this would require credible underwriting, effective risk management, investor confidence and a financing structure capable of matching long-term assets with appropriate sources of capital.
Government And Private Developers Need Clearer Responsibilities
Ogiemwonyi argues that government should focus primarily on creating an enabling environment for housing development.
Its responsibilities would include providing access to land, improving title administration, delivering roads, water and electricity, and simplifying regulatory processes.
Predictable property rights would also help households and developers use real estate more effectively as collateral, potentially expanding access to formal finance.
Private developers and individuals would undertake construction, while banks and mortgage institutions would originate and service loans.
A clearer division of responsibilities could strengthen accountability, improve efficiency and allow public institutions to concentrate on the infrastructure and policy interventions needed to make housing more affordable.
Housing Can Support Jobs And Wealth Creation
Housing contributes to more than household welfare. It also supports economic activity across construction, building materials, professional services and financial markets.
A deeper housing market could create jobs, expand household asset ownership and provide additional long-term investment instruments for the financial sector.
It could also broaden property-related government revenues, provided that taxation remains predictable and does not impose excessive costs on development or ownership.
For Ogiemwonyi, the wider economic benefits depend on building a housing system that connects finance, land, infrastructure and effective institutions.
Affordability Must Remain The Policy Priority
Nigeria’s housing challenge requires more than increased construction. It demands a financing framework capable of connecting long-term capital to households that need affordable homes.
A stronger mortgage market, supported by housing bonds, mortgage-backed instruments, efficient land administration and credible lending standards, could expand the supply of housing finance.
The proposed reforms would also require effective coordination among federal and state governments, housing agencies, private developers, mortgage lenders and institutional investors.
Ultimately, affordability must remain central to housing policy. Without that focus, additional construction concentrated in the higher end of the market will do little to ease the pressures facing most Nigerian households.
The central policy question is therefore not simply how Nigeria can build more houses, but how it can establish institutions and financing mechanisms that enable more people to afford them.