
BEYOND BANK LOANS: HOW REAL ESTATE DEVELOPERS CAN RAISE BILLIONS THROUGH THE CAPITAL MARKET
By Africa International Housing Show (AIHS)*
For decades, many real estate developers in Nigeria have depended heavily on commercial bank loans, personal savings, land sales, off-plan subscriptions and deposits from prospective homeowners to finance housing developments. Unfortunately, these traditional financing arrangements have not provided the scale of long-term capital required to address the country’s enormous housing challenges.
With high lending rates, rising construction costs, inflation and limited access to affordable development finance, the time has come for credible real estate companies to explore alternative funding opportunities available through Nigeria’s capital market.
One important but relatively underutilised financing instrument in the housing sector is the **corporate bond*
Through the issuance of bonds and other structured debt instruments, qualified real estate companies can potentially raise billions of naira from institutional and other eligible investors to finance housing estates, infrastructure, affordable rental accommodation and large-scale property developments.
However, accessing this opportunity requires financial discipline, transparency, credible project documentation and an understanding of capital market regulations.
Understanding How Bonds Work in Real Estate Financing
A bond is essentially a financial instrument through which a company borrows money from investors under agreed repayment conditions.
Unlike equity financing, where investors acquire ownership interests in a company, bond financing generally allows developers to raise capital without surrendering ownership of their businesses.
For instance, a credible real estate development company seeking ₦10 billion to construct a housing estate may approach the capital market through an appropriately structured bond issuance.
Investors subscribe to the bond, and the developer undertakes to pay agreed interest, where applicable, and repay the principal according to the terms of the instrument.
Depending on the structure, repayment may be supported by proceeds from property sales, rental income, other corporate revenues or dedicated project cash flows.
This financing arrangement can provide developers with access to larger pools of capital than may be available through conventional borrowing arrangements.
Nevertheless, bonds create legally enforceable financial obligations, and developers must demonstrate a credible capacity to meet them.
Types of Bonds Real Estate Companies Can Explore
Several financing instruments may be suitable for different categories of property development.
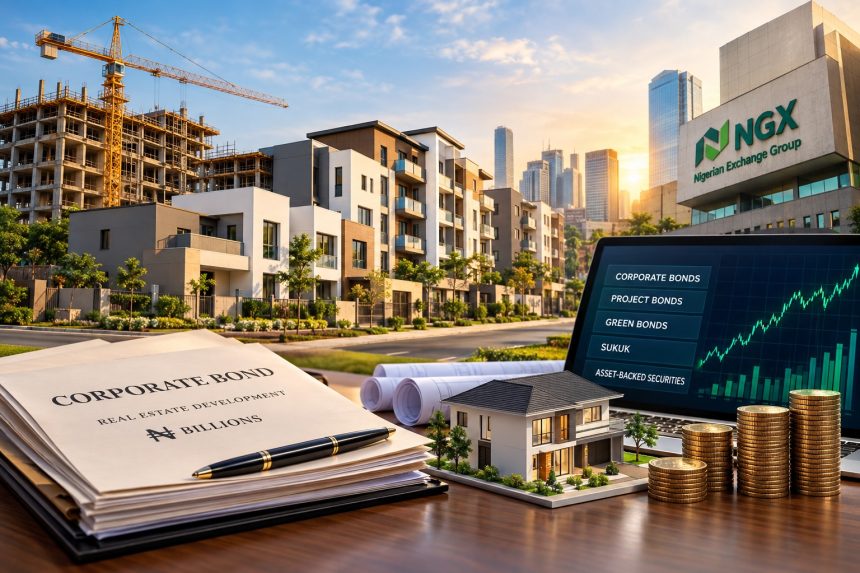
1. Corporate Bonds
These are debt instruments issued by eligible companies to raise money for business expansion, construction projects, refinancing and other permitted corporate purposes.
A well-established real estate company with a credible financial history may explore corporate bonds to finance several developments simultaneously.
2. Project Bonds**
Project bonds are structured around the financing of specific projects, with repayment arrangements linked to the project’s financial structure and available revenue sources.
They may be considered for large housing estates, mixed-use developments and infrastructure projects where predictable cash flows can be demonstrated.
3. Green Bonds**
Green bonds provide financing for projects that meet recognised environmental eligibility requirements.
Real estate companies developing qualifying energy-efficient buildings, environmentally sustainable housing estates or other eligible green infrastructure may explore this financing option.
4. Sukuk
Sukuk are Sharia-compliant capital market instruments structured around eligible assets and contractual arrangements.
They can offer an alternative financing pathway for suitable real estate and infrastructure developments.
*5. Asset-Backed Securities**
These instruments enable eligible issuers to raise financing against defined pools of financial assets, such as qualifying mortgage receivables.
They may become increasingly relevant as Nigeria’s mortgage and housing finance markets develop.
What Makes a Real Estate Company Qualified to Raise Bonds?
One of the most important lessons for Nigerian property developers is that the capital market operates on a different level of financial scrutiny from ordinary land marketing and property advertising.
A company cannot simply announce a multibillion-naira bond programme and expect investors to provide funding.
Investors, regulators and transaction advisers will ordinarily examine several critical factors.
Corporate Governance: The company must demonstrate sound management, transparent ownership structures, credible directors and effective internal controls.
Audited Financial Statements:** Investors need reliable information about the company’s financial performance, assets, liabilities and financial obligations.
Project Delivery Track Record:** A history of completed housing projects can strengthen investor confidence. Companies that repeatedly advertise estates without delivering infrastructure or completed buildings may struggle to attract serious institutional financing.
Valid Land Titles and Development Approvals Projects must have verifiable land documentation, planning approvals and other necessary legal authorisations.
Financial Projections: Developers must demonstrate how projects will generate sufficient income to service and repay the proposed debt.
Creditworthiness:Depending on the transaction, investors may require credit ratings, guarantees, collateral arrangements or other credit enhancements.
The message is clear: **The capital market rewards credibility, transparency and financial discipline, not publicity alone.**
How Can a Real Estate Company Begin the Process?
A developer interested in raising capital through bonds should ordinarily begin by consulting an issuing house or investment bank registered with Nigeria’s Securities and Exchange Commission.
The issuing house can assess the company’s readiness, determine an appropriate financing structure and coordinate the professionals required for the transaction.
The process may involve preparing a feasibility study, reviewing financial statements, engaging legal advisers, conducting due diligence, obtaining credit ratings where required, appointing trustees and satisfying applicable regulatory requirements.
Depending on the structure, the company may also consider listing or quoting its securities through recognised market platforms such as Nigerian Exchange Limited or FMDQ Securities Exchange.
It is important to recognise that public companies, private companies and special-purpose financing vehicles may face different regulatory requirements. The appropriate route must be determined by qualified capital market professionals.
Can Small and Medium-Sized Developers Benefit?
An important question is whether bond financing should remain the exclusive preserve of large real estate companies.
Although smaller developers may lack the financial strength or transaction scale required for individual bond issuances, innovative financing structures could create opportunities for them.
For example, a professionally managed financing vehicle could potentially aggregate eligible projects from several credible developers and raise capital through a properly structured debt programme.
Such arrangements would require strong governance, independent project assessments, credit enhancement where necessary and effective investor protection.
This could provide a pathway for credible medium-sized developers to participate in institutional housing finance without each company independently issuing a large bond.
However, pooling developers does not eliminate credit risk. Each participating project must meet strict commercial and financial standards.
The Role of Pension Funds and Institutional Investors
Nigeria has significant pools of long-term savings managed by pension fund administrators, insurance companies and other institutional investors.
These institutions could potentially play a greater role in financing suitable housing developments through properly structured and eligible capital market instruments.
Housing bonds with appropriate credit quality, risk management, investor protection and repayment arrangements may attract institutional interest.
However, pension fund investments must comply with National Pension Commission regulations, and no developer should assume that pension funds are automatically available for property financing.
Housing investment must compete with other asset classes on the basis of risk, return, liquidity and regulatory eligibility.
Why Nigeria Must Develop a Stronger Housing Bond Market
One of the structural challenges facing Nigeria’s housing sector is the mismatch between short-term financing and long-term property development.
Housing projects often require substantial upfront expenditure on land, roads, drainage, electricity, water, building materials and construction.
Developers who rely primarily on short-term borrowing or advance payments from buyers may face financial pressure when construction costs rise or property sales slow down.
Properly structured long-term capital market financing could help reduce this mismatch.
It could also support greater transparency because bond issuers are generally subject to defined disclosure, governance and investor reporting obligations.
Nevertheless, issuing bonds does not automatically make housing affordable. High coupon rates, transaction costs and weak project cash flows can make bond financing expensive.
Developers must therefore carefully evaluate whether a proposed bond offers a sustainable financing advantage.
Africa International Housing Show Calls for Greater Capital Market Education
The Africa International Housing Show (AIHS) believes that improving access to sustainable housing finance requires greater collaboration between property developers, capital market operators, institutional investors, mortgage institutions, regulators and government.
As an international platform connecting housing industry stakeholders, investors, policymakers and professionals, AIHS recognises the importance of expanding financing knowledge among real estate entrepreneurs.
Many developers understand how to acquire land, advertise estates and sell plots, but fewer have sufficient knowledge of corporate finance, debt structuring, capital market fundraising and institutional investment requirements.
This knowledge gap deserves urgent attention.
There is a need for more practical education on bond issuance, project financing, credit ratings, financial reporting, investment readiness and alternative funding structures.
AIHS therefore encourages credible real estate developers to begin strengthening their corporate governance, financial records and project delivery systems so they can become better positioned to access institutional capital.
The organisation also advocates stronger collaboration between the housing industry and Nigeria’s capital market institutions to explore financing mechanisms capable of supporting affordable housing development.
Beyond Selling Land: Building Financially Sustainable Real Estate Companies
The future of Nigeria’s real estate industry cannot depend indefinitely on the continuous sale of undeveloped plots and collection of advance payments from prospective homeowners.
Developers must increasingly embrace business models built around project delivery, recurring income, professional management, financial accountability and sustainable access to capital.
Companies seeking to attract serious investors must demonstrate that they are capable of transforming investment funds into completed, functional and commercially viable housing projects.
This is particularly important at a time when Nigerians are demanding greater accountability from property developers.
The industry must move from a culture dominated by aggressive marketing to one that places greater emphasis on financial credibility and delivery performance.
Conclusion
Nigeria’s capital market offers important opportunities for real estate companies seeking to diversify their sources of finance.
Corporate bonds, project bonds, green bonds, Sukuk and other structured financing instruments could help qualified developers mobilise capital for housing and infrastructure development.
But these opportunities are not available merely because a company is registered as a real estate business.
They require credible financial records, regulatory compliance, professional governance, viable projects and demonstrated repayment capacity.
For Nigeria to make meaningful progress in housing delivery, the real estate industry must move beyond excessive dependence on bank loans, land sales and off-plan subscriptions.
*The next generation of successful real estate developers will not be defined only by how much land they control or how many estates they advertise, but also by their ability to attract responsible investment, manage capital professionally and deliver completed homes.
Africa International Housing Show (AIHS)
*Housing Opportunities Start Here.*
www.africahousingshow.com